Current Startup and Venture Capital News for September 17, 2026: Temporal Mega Round in AI Infrastructure, Unicorns Exein and Open Cosmos, Semiconductor Deal EUCLYD, Wave of Rounds in "Physical AI" in China, Federal Reserve Meeting, Holtec IPO, and Anthropic Listing Preparations
As of mid-September 2026, the global venture capital market is showcasing a notable shift: capital is moving away from "wrappers" around language models towards the infrastructure that makes artificial intelligence reliable, affordable, and applicable in the physical world. In the past 48 hours, venture funds have closed a series of substantial funding rounds—from $550 million in Temporal to €300 million in Open Cosmos—while Europe welcomed two new unicorns in a single day. Concurrently, investors are reassessing capital cost models: the Federal Reserve meeting on September 16, where markets priced in over 90% probability of the first rate hike since 2023, sets a new framework for valuations of late-stage startups.
Key topics in the venture agenda for Thursday, September 17, 2026:
- Temporal Mega Round. $550 million at a valuation of $12.55 billion—AI agent infrastructure is becoming a standalone asset class.
- New Unicorns in Europe. Italian Exein ($1.7 billion) and British Open Cosmos (over $1 billion) confirm demand for cybersecurity and space.
- Semiconductors and "Physical AI." EUCLYD raises over €200 million, while China funds robotics and chip inspection.
- Macro Factors. The Fed and expensive venture debt are changing the math for late-stage rounds.
- IPO Window. Pricing of Holtec and Orion180, anticipation of Anthropic's prospectus and Oura listing.
- Russia and CIS. The market has contracted nearly by half, with capital concentrated in five major deals.
Deal of the Day: Temporal Raises $550 Million for AI Agent "Reliability"
The platform Temporal, which develops infrastructure for durable execution for distributed applications and AI agents, has closed a Series E round at $550 million with a valuation of $12.55 billion. The round was led by Lightspeed, with co-investors including Wellington Management, Growth Equity at Goldman Sachs Alternatives, and Tiger Global; participants also included T. Rowe Price and SV Angel, while returning investors comprised a16z, Sequoia, Index, and GIC.
The dynamics are striking: just in February 2026, the company was valued at $5 billion during its Series D, indicating that its valuation has more than doubled in just seven months. The justification lies in operational metrics that are rarely seen in startups of this scale:
- Annual revenue exceeded $250 million, with over 200% year-over-year growth;
- Net revenue retention (NDR) has remained above 200% since February;
- In August, the platform processed 1.9 trillion billable actions, representing over 350% growth;
- The number of paying customers reached 4,300 (+139%), including OpenAI, Netflix, Snap, NVIDIA, and JPMorgan Chase.
For venture investors, Temporal is a marker of the new thesis: the victor is not necessarily the one training the best model, but the one controlling how models execute multi-step processes in production.
Europe: Two New Unicorns in a Single Day
Exein – Europe's Most Valued Cybersecurity Startup
Roman startup Exein has raised $270 million at a valuation of $1.7 billion in an oversubscribed round led by Headline. The deal included participation from Sofina, Goldman Sachs, the European Investment Bank group, KfW Capital, and T.Capital, as well as previous investors Balderton, HV, and Lakestar. The cumulative amount of capital raised has exceeded $600 million, with the valuation increasing 30 times over two years, and the ARR quadrupling in the first half of 2026.
The company protects "physical AI"—robots, drones, autonomous transport, and industrial devices—at the core operating system level. Its technology covers over 2 billion connected devices, with around half of its revenue generated in the Asia-Pacific region. The funds will be used for expansion in the U.S., M&A activities, and the development of its proprietary foundational model for machine security.
Open Cosmos – A Profitable Space Unicorn
The British satellite manufacturer Open Cosmos has closed a Series C round at €300 million (approximately $348 million) with a valuation of over $1 billion. The round was led by Lightrock and ETF Partners, with participation from the BCI pension fund, Institut Català de Finances, Entrepreneurs First, Phoenix Court, and the British NSSIF, while Claret Capital provided venture debt. The company produces up to one satellite per day across four facilities, has shown profitable growth for five consecutive years, and secured contracts worth over $370 million in three and a half years. The round was oversubscribed and purposefully aimed at European investors—a signal that sovereign space infrastructure is becoming a priority for continental capital.
Semiconductors: EUCLYD Tackles Inference Costs
Eindhoven-based startup EUCLYD has raised over €200 million in a Series A round, co-led by Samsung, Somerset Capital Partners, the Scaleup Europe Fund managed by EQT, and Innovation Industries. Former ASML CEO Peter Wennekes has been appointed as the chairman of the board. The company develops specialized ASICs and data center-level systems that reduce energy consumption and memory bandwidth requirements when serving large models. The thesis is simple: as inference becomes the largest computational workload, the economics "per token" becomes a distinct semiconductor opportunity regardless of whose model wins.
Asia: China Dominates "Physical AI" Rounds
The Asian trading day has seen a cluster of deals unified by a single rationale—funding components and operating systems for robots rather than demonstration prototypes:
- ENCOS (Nanjing) – over 300 million yuan Series B led by CITIC Goldstone for the production of integrated robotic joints and manipulators;
- Yincheng Intelligence (Shanghai) – around 100 million yuan Series A along with a comparable size order from SF Express for sorting robots;
- Kangwei Vision (Shenzhen) – around 100 million yuan for optical inspection of AI server boards;
- Nutshell Therapeutics – C1 round in the tens of millions from Trustbridge and Decheng with a candidate already in clinical phase I.
Completing the picture are Hong Kong's Qupital with $300 million in capital commitments for trade financing, Stockholm's Tandem Health securing $100 million in Series B from EQT, and Tokyo's Yoom with its first external round of ¥700 million for orchestrating AI agents in corporate processes.
Macro: The Fed, Venture Debt, and the New Cost of Capital
The Fed's rate has been maintained in the range of 3.50–3.75% since December 2025; however, U.S. inflation remained at 3.4% in August due to energy shocks sparked by the Middle East conflict. Ahead of the September 16 meeting, futures priced in about a 93% probability of a 25 basis points hike—the first since 2023. For the venture market, this signals a scenario of "expensive money for a long time": floating credit lines tied to SOFR are being repriced every 90 days, and every 25 basis points adds approximately $25,000 in annual expenses for every $10 million in debt. Late-stage funds are already adjusting multiples, while companies with growing metrics like Temporal continue to attract capital at premium valuations.
IPO: The Window is Open, but Selective
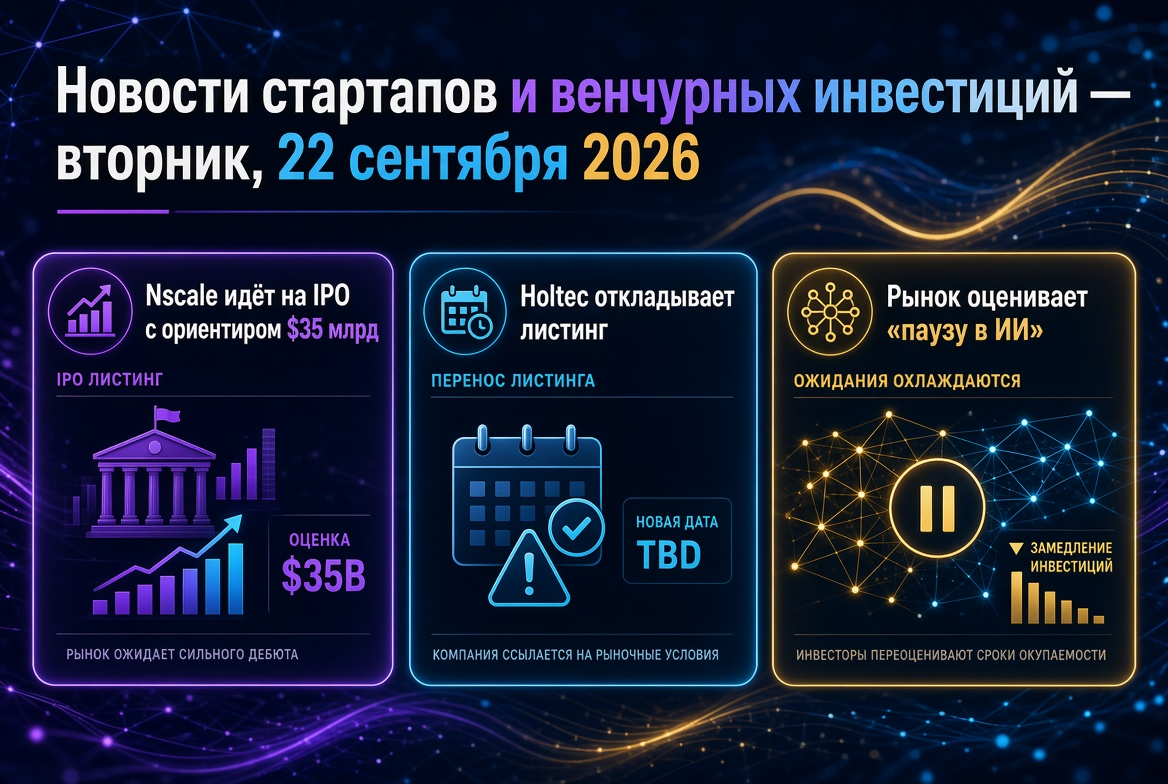
2026 is on track for the strongest performance of the IPO market since 2021: 331 applications have been submitted, and 280 deals have been completed so far this year. For Thursday, September 17, pricing is scheduled for two listings on Nasdaq: nuclear company Holtec is offering 50 million shares at $15–18 (approximately $850 million), while insurer Orion180 aims to raise up to $340 million at a valuation of around $1.7 billion. Smart ring manufacturer Oura, which submitted its application on September 3, anticipates a listing closer to the end of the month.
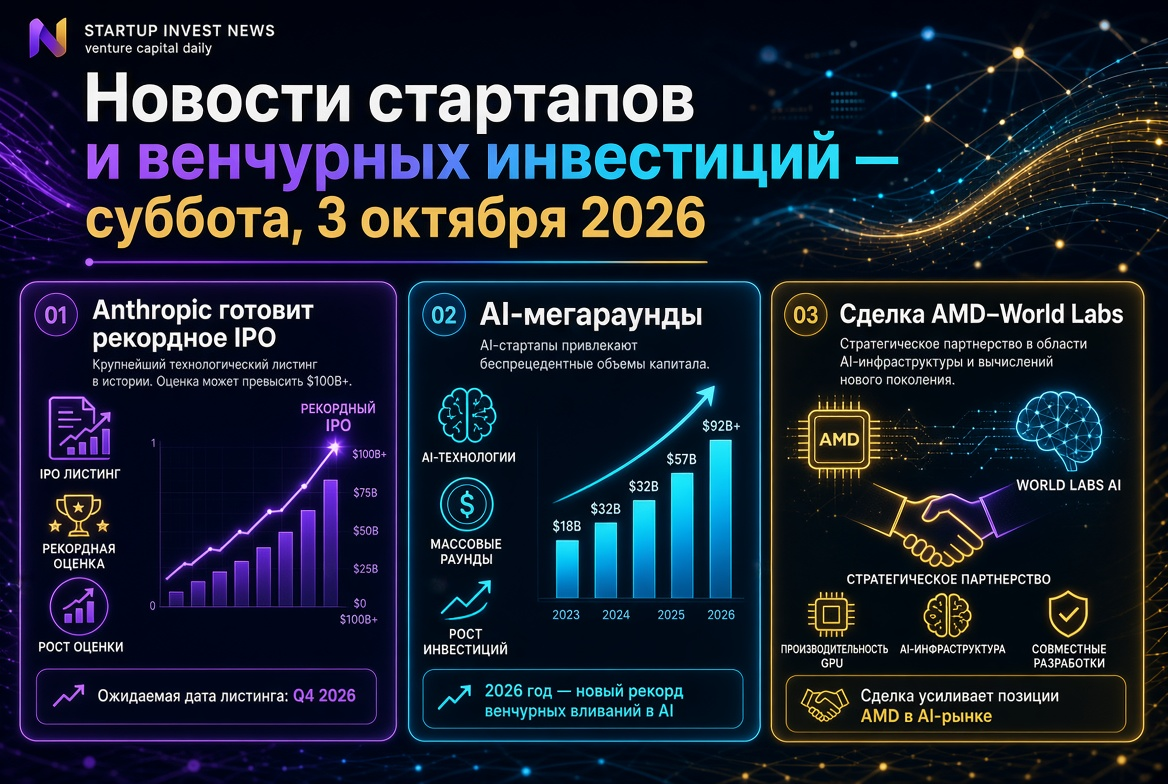
The main event of the season is Anthropic. Following a confidential S-1 filing in June and a Series H round at $65 billion with a valuation of $965 billion, the company is reportedly preparing a public prospectus for late September and a roadshow by mid-October, targeting a valuation of up to $2 trillion. Annual revenue exceeded $65 billion by the end of July. The public financial data of this AI market leader will serve as a benchmark for reevaluating the entire private AI ecosystem.
Russia and CIS: Concentration over Growth
The Russian venture market shrank by 48% year-on-year in the first half of 2026, down to 4.6 billion rubles, and the number of active investors fell from 50 to 33. Private funds accounted for 67% of the volume (3.1 billion rubles in 21 deals), while corporate investments dropped by 54% to 0.4 billion rubles. About 60% of the market has been captured by the five largest deals, with the "Architect AI" round at 1.1 billion rubles accounting for nearly a quarter of the half-year volume. No foreign deals have been recorded—the market has become entirely domestic, with capital directed towards mature B2B companies with clear revenue streams.
What This Means for Venture Investors
- The infrastructure layer is more valuable than the model layer. Temporal, EUCLYD, and DeepKernel show that the premium goes to those who control execution, computation, and data.
- "Physical AI" requires proof. Orders from SF Express for Yincheng and clinical phases from Nutshell are valued more than demonstrations.
- Sovereignty is becoming a budget line item. European rounds for Open Cosmos and EUCLYD have been raised with a focus on local capital.
- Expensive debt is changing round structures. It is time to reconsider floating credit lines and factor in higher rates in models until the end of the year.
- The IPO window is open for quality. Anthropic's prospectus will serve as a benchmark for valuations of private AI companies.
Daily Recap
The venture market on September 17, 2026, appears simultaneously generous and demanding: record rounds and new unicorns coexist with tightening criteria and rising capital costs. Investors are paying for scarce assets—efficient chips, real operational data, deeply integrated workflows, and secure infrastructure. Intelligence is becoming cheaper, while the systems that transform it into reliable economic outcomes are becoming more expensive. This is where capital is heading.