Current News on Startups and Venture Investments as of September 11, 2026: Record European Round for Mistral AI, IPO Delay for Anthropic, August Mega-Round Statistics, M&A Deals, and Overview of the Russian Venture Market for Investors and Funds.
The second week of September 2026 reaffirms the main thesis of the year: venture investments continue to reach record volumes but are becoming increasingly concentrated in structure. While private valuations of frontier labs approach one trillion dollars, Europe is witnessing, for the first time in a long time, deals comparable to those in the U.S., and the IPO market is once again testing investors' nerves with anticipation of the largest listings in history.
Below are the key events and trends shaping the agenda for startups and venture investments for Friday, September 11, 2026:
- Mistral AI closed a Series D round at $3.5 billion with a valuation exceeding $24 billion—the largest venture deal in the history of European AI.
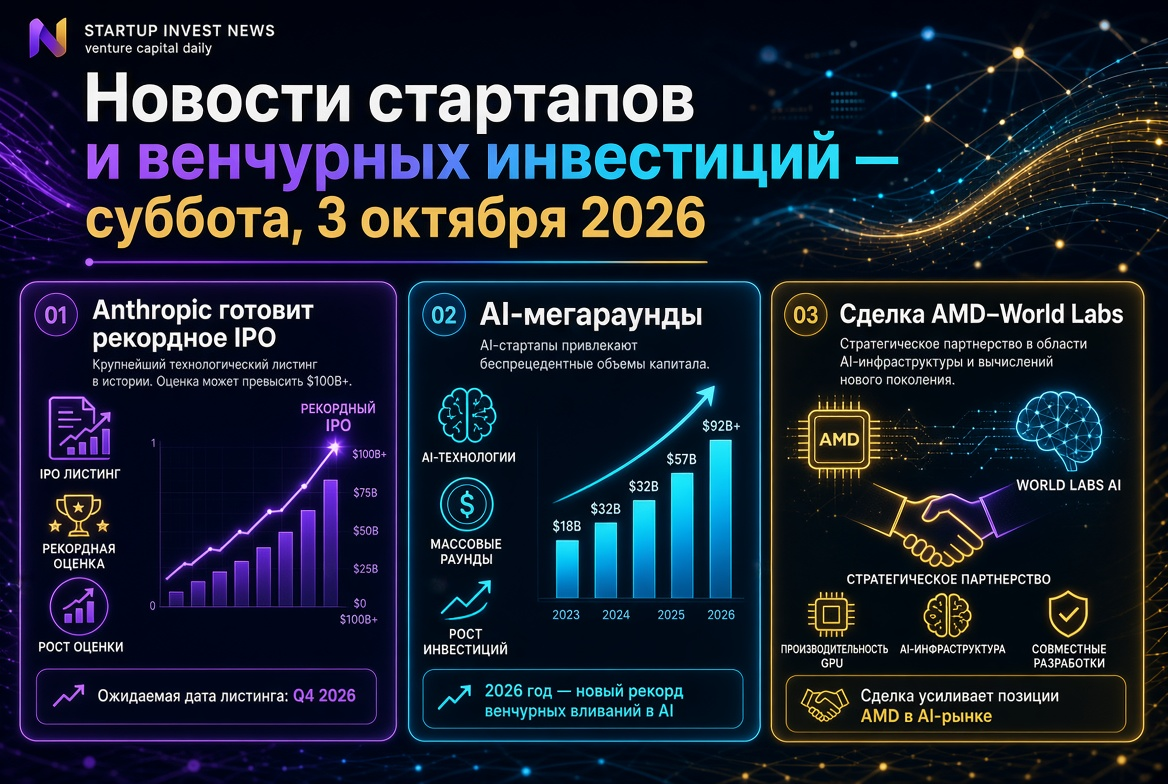
- Anthropic has postponed its IPO marketing launch until mid-October, narrowing the fall window for major tech placements.
- August brought $42 billion in global funding and seven rounds of one billion dollars or more, including $5 billion for Databricks.
- AI infrastructure remains the main magnet for capital: Gimlet Labs raised $300 million at a valuation of $3 billion.
- M&A and exits are gaining momentum: Nvidia is acquiring Hugging Face for $12.9 billion, while Unitree Robotics surged by 460% on its first day of trading.
- The Russian venture market shrank by 48% in the first half of the year, while the median check increased.
Headline of the Day: Mistral AI and the New European Record
Paris-based Mistral AI announced the raising of $3.5 billion in its Series D round, led by Samsung Electronics with participation from the EQT-managed Scaleup Europe Fund and existing investor PSG Equity. The company’s valuation nearly doubled in one year—growing from $13.7 billion to over $24 billion—while the total capital raised since its founding in 2023 reached $7.5 billion.
This deal is important for venture funds for three reasons. Firstly, Mistral retains its status as the only European frontier lab among seven private AI companies with valuations exceeding $20 billion—most are based in the U.S. and China. Secondly, the strategic involvement of a semiconductor chip manufacturer confirms a trend: industry players are increasingly entering the equity of AI startups, competing with traditional funds for allocation. Thirdly, Mistral’s focus on sovereign models that businesses can deploy on their own infrastructure finds demand among Airbus, ASML, BMW, and HSBC—over 125 corporate clients in 20 countries.
The round underscores a turnaround in the European venture market: in the second quarter, startups in the region raised $24 billion, marking the best result in four years. Alongside Mistral, significant AI rounds this year include Isomorphic Labs ($2.1 billion) and Nscale ($2 billion at a valuation of $14.6 billion).
Anthropic Postpones IPO: Fall Window Narrows
Anthropic, which submitted a confidential S-1 filing on June 1, now plans to start its placement marketing no earlier than mid-October. Valued at $965 billion following its Series H round of $65 billion, the company remains a leading contender for the year’s largest IPO following the June debut of SpaceX, which raised $75 billion with a $1.77 trillion valuation.
The delay has direct implications for the venture ecosystem:
- Liquidity for LPs is deferred. Shareholder funds of Anthropic—from Sequoia and Coatue to Altimeter and D1—will receive distributions later than anticipated in their third-quarter models.
- Other issuers are waiting. Mid-cap companies are reluctant to go public until the market “digests” this AI mega-listing and settles on their appetite.
- OpenAI is targeting 2027. The company’s CFO has informed staff that public status is scheduled for next year, noting that racing against competitors is not a priority.
Secondary markets still value Anthropic at $1.05–1.15 trillion, reflecting investors' confidence in the subsequent placement but also raising the bar for public market expectations.
August by the Numbers: $42 Billion and a Series of Billion-Dollar Rounds
Global venture investments in August totaled $42 billion, spread over just more than 1,500 startups. This is a 25% decline from July’s $56 billion, but 122% higher than August of last year—a typically quiet month.
Largest Deals of the Month
- Databricks — $5 billion at a valuation of $190 billion; the company has added $56 billion to its market cap over six months.
- Hadrian (defense manufacturing), River AI (custom model fine-tuning), Valar Atomics (nuclear energy), Poolside (code automation), Base Power (home storage), and Yuanxin Satellite (low-earth orbit communication) — each raised $1 billion or more.
Notably, five of the seven recipients of billion-dollar rounds had raised capital less than a year ago. The acceleration of cycles between rounds is a direct indication of how quickly investors are doubling down on companies they believe will become future tech giants.
AI Infrastructure: Capital Flows to “Pickaxes and Shovels”
Early September confirms that investors are funding not only models but also the layers of inference and computation. Gimlet Labs raised $300 million in its Series B round led by Andreessen Horowitz at a valuation of $3 billion—just six months after a Series A of $80 million. New investors include Arm and M12, Microsoft’s venture arm, underscoring chipmakers’ strategic interest in multi-silicon architectures.
This week also saw rounds closed for Wonderful ($550 million, Series C, Insight Partners), Forus ($160 million, Series C, Bain Capital Ventures), Clay ($115 million, Series D, Wellington), and Savvy Wealth ($100 million, Series C). Semiconductor funding in 2026 is nearly 50% ahead of last year's total, while investments in physical AI—robotics, aerospace, and manufacturing—reached $47.4 billion for the first half of the year.
Exits and M&A: The Exit Market Gathers Pace
The second quarter marked the strongest period for exits since 2021, and fall continues this trend:
- Nvidia announced its intention to acquire the open-source platform Hugging Face for $12.9 billion.
- Milan-based Bending Spoons is acquiring Airtable for approximately $1.3 billion.
- Unitree Robotics debuted on the Shanghai Stock Exchange at a valuation of around $9 billion, soaring 460% on its first trading day.
- Hong Kong is hosting a series of tech placements: Shenzhen Longsys raised around $785 million, while Excelland Robotics is listing under special provisions for tech companies.
In the U.S., 238 IPOs have taken place since the beginning of the year—slightly more than the previous year, but the majority of the raised capital has come from a small number of mega-deals, including Cerebras ($5.6 billion) and Quantinuum.
Capital Concentration: The Two-Speed Market
The first half of 2026 ended with a record $510 billion in global venture investments, surpassing the total amount for all of 2025. However, OpenAI and Anthropic together accounted for 43% of all funds, while nearly 80% of funding went to American companies from seed to growth stage. For investors, this implies significant stratification: a narrow group of late-stage companies is closing rounds in the hundreds of millions and billions, while early-stage teams face increasing demands for revenue, customer retention, and unit economics.
Russia and the CIS: The Market Shrinks, Checks Increase
The volume of Russian venture investments in the first half of 2026 decreased by 48% year-on-year, to 4.6 billion rubles, while the number of deals fell by 45%, to 54. The median check, however, increased by 23%, reaching 24.6 million rubles. Almost half of the total volume came from three deals: the corporate AI developer “Arkhitek AI” raised 1.087 billion rubles, while Callisto Vision and Robo received 700 million and 500 million rubles respectively from the investment group Kama Flow.
The market structure is changing: private funds accounted for 67% of investments but reduced their activity; business angels decreased their investments by 68%, and the number of investors fell from 50 to 33. State funds became the only category that increased the number of deals. Capital is consolidating around stages A and B2B projects in AI, cybersecurity, and domestic software, where investors demand proven revenue even at early stages.
What This Means for Venture Investors and Funds
Practical Takeaways of the Week
- Corporate strategists are the new competition for allocation. Samsung in the Mistral round, Arm and Microsoft in Gimlet Labs: chip manufacturers are directly acquiring access to demand.
- Plan for liquidity with a buffer. The postponement of Anthropic's IPO shifts distributions and may delay other companies' listings into the fourth quarter.
- Europe has become investable on scale. Three European AI rounds over $2 billion this year—this is an argument for geographical diversification.
- Speed of rounds is a risk factor. Six-month intervals between Series A and B with exponential valuations require rigorous checks of contractual revenues.
Conclusion: Record Volume Amid Growing Selectivity
As of September 11, 2026, the venture market combines record capital inflows with unprecedented concentration. The record set by Mistral AI and the wave of infrastructure rounds signal that appetite for artificial intelligence remains strong; however, the postponement of Anthropic's IPO serves as a reminder: the path to public liquidity remains challenging even for the priciest unicorns. Funds that can combine access to mega-deals with discipline at early stages will be in the best position when the fall exit window finally opens.