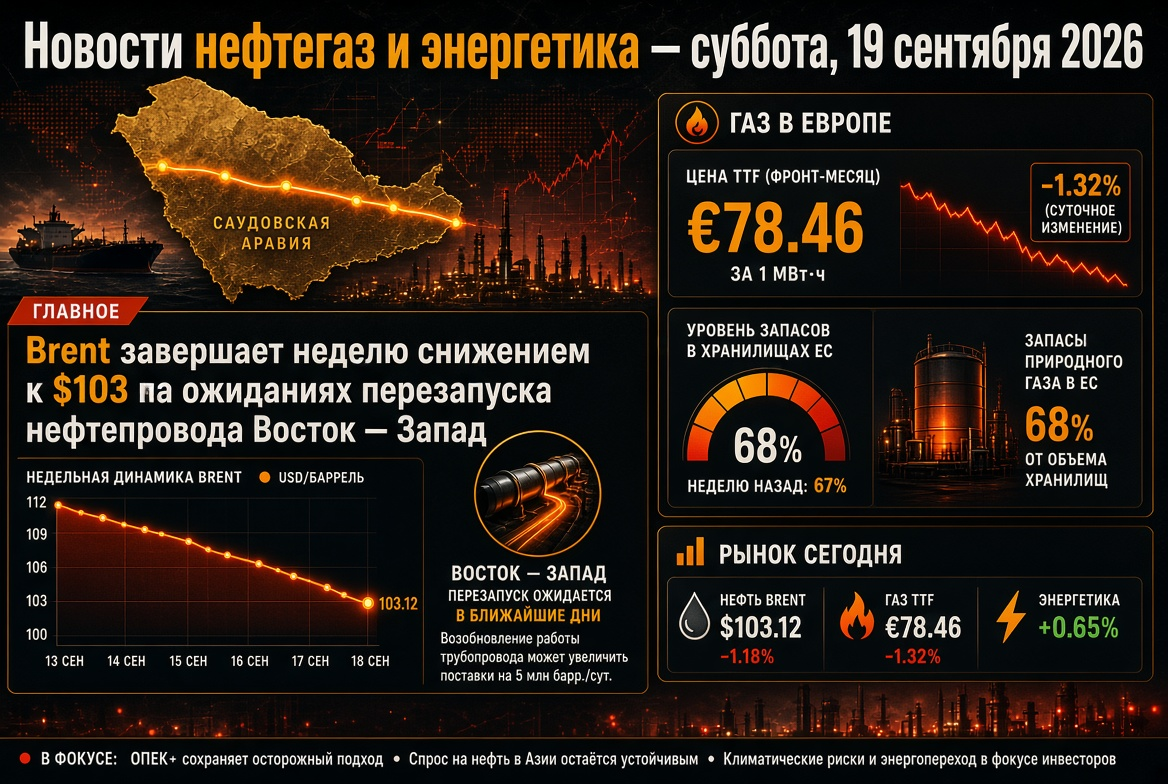
Oil and Gas News and Energy: Friday, September 11, 2026 — Brent Stays Above $102 After Largest Tanker Attack in the Strait of Hormuz, Gas in Europe Over €80
The global fuel and energy sector enters Friday, September 11, 2026, in a state of full price shock. Brent oil trades above $102 a barrel for the first time since late May, the European gas benchmark TTF has surpassed €80 per MWh for the first time since January 2023, and underground gas storage in the EU is only two-thirds full, compared to a seasonal norm of over 80%. The trigger was the largest wave of attacks on shipping in the Strait of Hormuz since the beginning of the war, coupled with a second front in the Red Sea. For investors, oil and fuel companies, refinery operators, and participants in the gas, coal, electricity, and renewable energy markets, the key question of the day is: how much more geopolitical premium can the global economy absorb before demand for energy sources begins to crumble.
Main Topic of the Day: Tanker Warfare in the Strait of Hormuz Escalates
In the early hours of Wednesday, the U.S. sunk five Iranian oil tankers in the Gulf of Oman and near Kharg Island as part of the "tanker for tanker" policy announced by Washington in early September. Tehran responded with attacks on ten vessels near the Strait of Hormuz and a missile strike on the U.S. base at Al-Asrak in Jordan. According to maritime monitors, at least one crew member of the tanker has died, with another reported missing. This marks the largest series of strikes on commercial shipping since the war began on February 28.
The physical outlook for the oil and gas market is deteriorating in three key areas:
- Expansion of the Restricted Zone. The IRGC has declared a maritime limited zone from Chabahar through the Gulf of Oman to the Arabian Sea, urging tanker crews near the coasts of Bahrain and Kuwait to leave their vessels immediately.
- Insurance and Freight. The new incidents effectively negate the availability of military risk coverage for vessels taking "unauthorized" routes, cementing transit through the strait at minimal levels.
- Environmental Risk. Damaged and partially submerged tankers in the Persian Gulf create a threat to desalination plants and coastal infrastructure in the Gulf countries.
Oil: Brent Above $102, WTI at $96 — Market Rewrites Price Expectations
Key oil market benchmarks as of Friday morning:
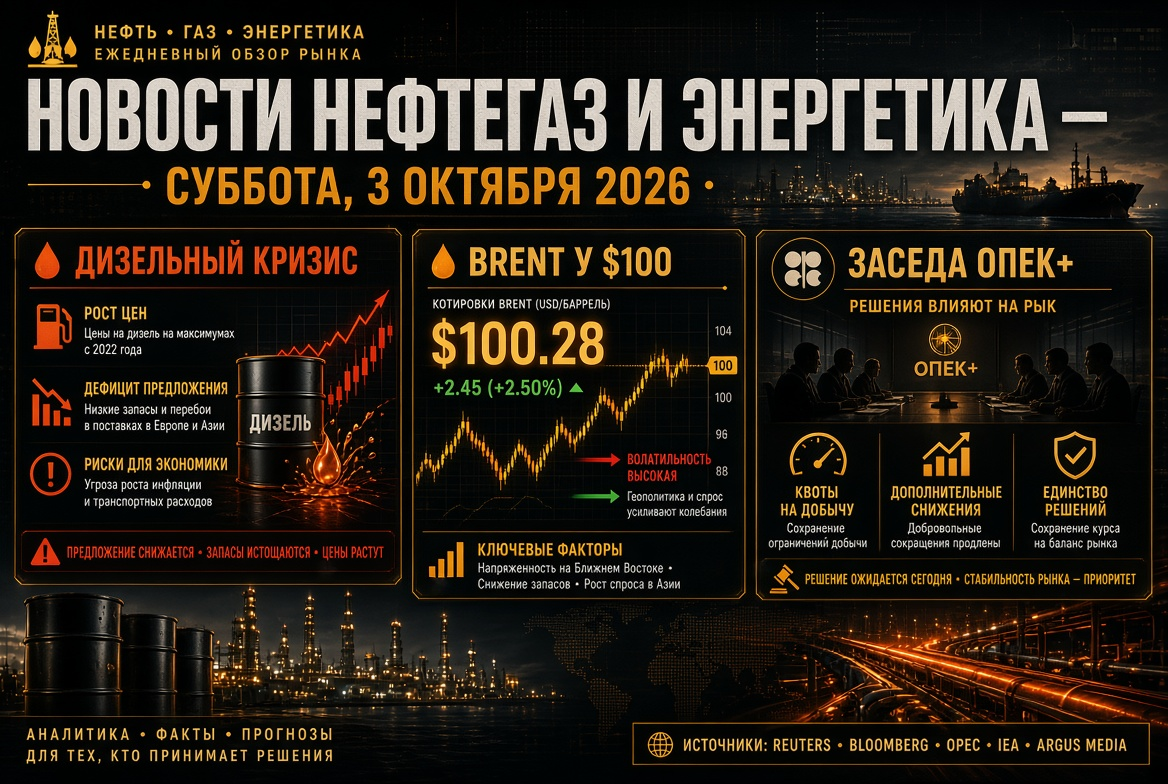
- Brent (November contract, ICE): rose by 3.4% on Wednesday to $101.21, and on Thursday briefly reached $102.4–102.9 — the highest since May 22. The yearly peak of $126.41 (April 30) remains a reference point for a "bearish" scenario in Hormuz.
- WTI (October contract, NYMEX): stabilized in the range of $96–97 per barrel.
- Forecasts: The September review from the U.S. Department of Energy set an average price for Brent at around $90 for the second half of 2026 and a decrease to $74 in 2027 — figures that already seem outdated just two days after publication. Long-term models from several Asian banks indicate prices of $113–114 within 12 months.
Stocks and Physical Balance
Global oil stocks, according to the U.S. regulator's estimate, have decreased by approximately 400 million barrels since the beginning of the year, and the recovery of production in the Middle East to pre-war levels has been pushed back to the second quarter of 2027. The U.S. strategic reserve stands at around 286.6 million barrels, the lowest since the early 1980s. Commercial oil stocks in the U.S. prior to the rescheduled weekly report on Thursday amounted to 424.5 million barrels, with refinery utilization at 98%; distillate stocks are 14% below the five-year average and are expected to fall below 100 million barrels by September.
OPEC+ and Monthly Reports
Seven OPEC+ countries maintained their October quotas unchanged during the meeting on September 6 after six consecutive months of production increases; the next meeting is scheduled for October 4. The monthly OPEC report, released on Thursday, sets the framework for demand after the August revision of the consumption growth forecast for 2026 to 0.58 million barrels per day. The International Energy Agency expects a decline in global demand by 1.6 million barrels per day amid a deficit of 1.8 million barrels per day in the third quarter and 8.3 million barrels per day of production in the Gulf, which remains halted.
Red Sea: Houthi Strikes on Jazan Refinery Open a Second Front for Oil Exports
While the market was focused on Hormuz, Yemeni Houthis launched a series of drone and missile attacks on the Saudi Aramco oil refinery in Jazan, with a capacity of 400,000 barrels per day, as well as on tank farms in Jazan and Abha from September 7–8. The facility has been halted, and the coalition led by Riyadh has promised to "respond to the sources of the threat." Simultaneously, the Houthis are engaging in combat near the port of Mocha, approaching the coast of Bab-el-Mandeb.
The significance of this front for the global energy market cannot be overstated: after the closure of Hormuz, Saudi Arabia redirected exports via the East-West pipeline to the Yanbu terminal, through which over 90% of the kingdom's maritime shipments flowed in June. The embargo declared by the Houthis has forced Asian cargoes to be rerouted through Suez, lengthening the journey by approximately 30 days and increasing freight costs. The threat to Yanbu represents a risk to the last significant bypass for Middle Eastern oil.
European Gas Market: TTF Above €80, Storage at 67% — Worst Start to Winter in 15 Years
The front-month TTF futures traded at €80.3–80.8 per MWh (around $985 per thousand cubic meters) on Thursday, surpassing €80 for the first time since winter 2023. Since the start of the conflict, prices have increased by approximately 150%, and over 120% since the beginning of the year. The British NBP neared 200 pence per therm. Growth drivers include:
- attacks on tankers in the Persian Gulf and the continued halt of LNG exports from Qatar;
- expansion of the JKM-TTF spread, drawing spot cargoes to Asia;
- record low storages: by September 9, EU gas reserves were filled to 67.33% (71.87 billion cubic meters) compared to a five-year average of around 84%.
The stock levels across countries remain critical: Germany — about 53%, Austria — 67%, France — 71%, Italy — 83%. European operators are injecting gas at record rates but at the highest prices in four years. In contrast, the American market saw Henry Hub drop below $2.8 per million BTU — transatlantic arbitrage for U.S. LNG exporters has reached historic levels.
LNG and Coal: Atlantic and Coal Generation Fill the Qatari Gap
Damage to the Ras Laffan complex has knocked out about 17% of Qatar's export capacity; full recovery is estimated to take up to five years and result in a loss of about $20 billion in annual revenue. Approximately 15 loaded LNG tankers are stalled behind Hormuz, with another two loading at the port — the market views the return of empty vessels home as a possible preparation for renewed shipments, but without passage through the strait, this remains a signal rather than a delivery.
For the coal sector, the LNG crisis means an unplanned demand window. The volume of switching from gas to coal in Europe and Asia is estimated at 40–60 million tons; coal generation in South Korea has increased by nearly 40%, and in Japan by more than 11%. Newcastle prices are holding around $130 per ton, supported by disruptions in Indonesian supplies, and global demand for coal in 2026 may increase by about 3% — to 9.1 billion tons.
Refined Products and Refineries: Refining Margins Rise, Russia Manually Controls Domestic Market
The global market for middle distillates remains the tightest segment: the deficit of diesel and jet fuel in Asia and Europe supports crack spreads at multi-year highs, while autumn maintenance at U.S. refineries temporarily reduces supply. The closure of Jazan removes over 200,000 barrels per day of diesel and naphtha export volumes from the market.
In Russia, the domestic market for refined products is operating manually:
- A complete ban on gasoline exports has been extended until January 31, 2027, with the stock exchange sales norm reduced to 10% (of which 8% are designated transactions), leaving the free market with about 2% of output;
- Exchange indices paradoxically decline despite the shortage: the average price of AI-92 at SPbMTSB on September 8 was 69,200 rubles per ton, while AI-95 was 71,800 rubles per ton, with the trading volume at 11,600 tons per session — three times below the norm;
- The reason is delays in shipments under exchange contracts for months due to refinery shutdowns following drone attacks; the price gap between baselines reaches 25,000 rubles per ton;
- The deficit is compensated by marine imports of gasoline from India, amounting to up to 400,000 tons per month.
Electric Power and Renewable Energy: Energy Transition as the Only Predictable Trend
Against the backdrop of commodity chaos, a structural shift in the energy sector is accelerating. Global electricity demand is projected to grow by 3.6% in 2026, supported by data centers, electric transport, and air conditioning, with renewable sources surpassing coal in global generation for the first time. Solar generation is expected to add around 600 TWh, ranking it second after hydropower. However, short-term vulnerabilities remain: in Europe, wind's share fell below 15% of demand at the beginning of the week, directly translating into rising gas and electricity prices. Each euro increase in TTF boosts the economics of storage, grid investments, and long-term contracts for "green" electricity.
Calendar: What to Watch for Energy Market Participants on Friday
- Market reaction to the monthly OPEC report and rescheduled weekly U.S. Department of Energy statistics on oil, gasoline, and distillate stocks.
- U.S. inflation data for August: the commodity shock increases the likelihood of tightened rhetoric from the Fed, which restrains speculative demand for oil.
- Statements from the coalition regarding Yemen and any signals about the state of the Yanbu terminal.
- Injection dynamics in European gas storage facilities and the JKM-TTF spread as an indicator of competition for spot LNG.
- Weekly results at SPbMTSB and decisions by Russian regulators regarding exchange norms and fuel imports.
Conclusions and Risks for Investors and Energy Sector Companies
- Oil. The $100 level has turned from resistance to support; the range of scenarios for the quarter ranges from $85 in the event of de-escalation to $120 in the case of new attacks on vessels and infrastructure in the Red Sea.
- Gas. Europe enters the heating season with historically low reserves; in a cold winter, TTF prices above €90–100 per MWh become the baseline rather than the stress scenario.
- Coal. Northeast Asia and parts of Europe will maintain elevated coal consumption until Qatari LNG supply is restored — at least until spring 2027.
- Refined Products and Refineries. Crack spreads support margins for refiners outside the conflict zone; in Russia, profits are being redistributed from independent gas stations to vertically integrated companies.
- Renewable Energy and Electricity. The long-term capital flow into solar and wind generation, storage, and networks remains the only resilient investment idea amid geopolitical volatility.
The bottom line for the global oil, gas, and energy sectors: two maritime chokepoints — Hormuz and Bab-el-Mandeb — are under fire simultaneously, and their condition, rather than OPEC+ quotas or macro statistics, will dictate prices for oil, gas, and electricity in the coming weeks. For energy market participants, scenario planning, supply logistics diversification, and hedging discipline are critically important.