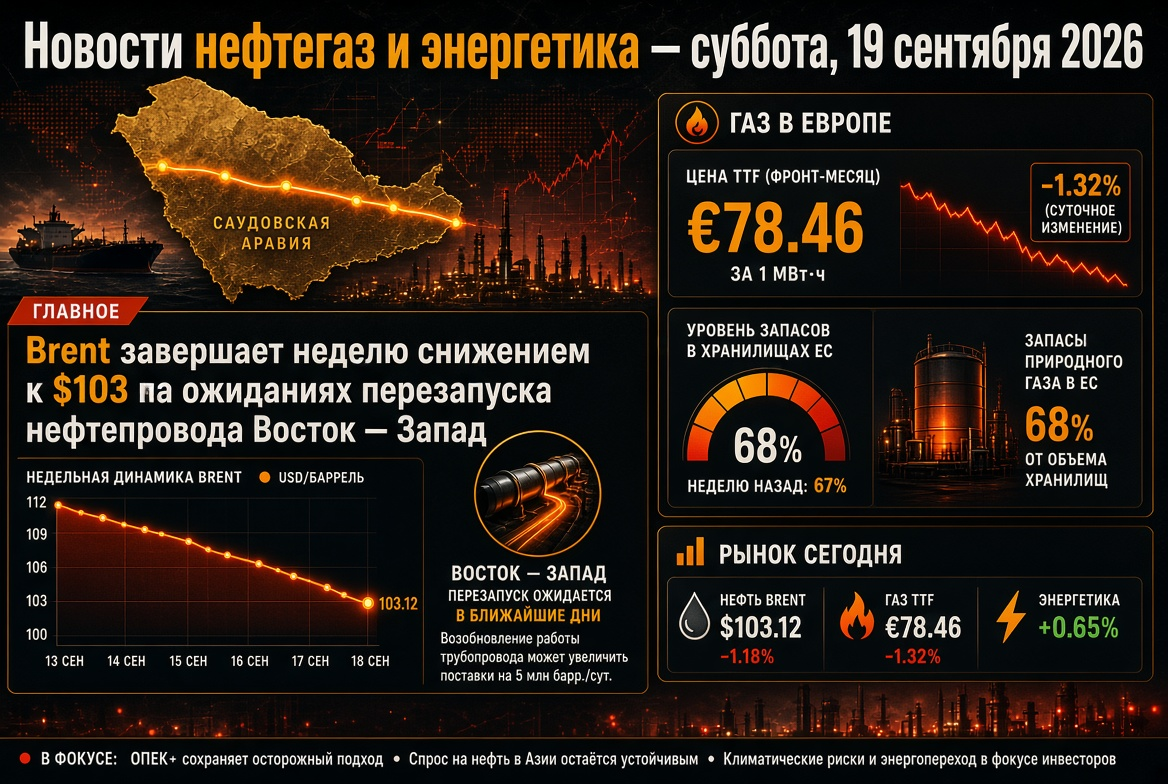
Key Topic of the Day: The Oil Market Between Record Deficit and Hope for “Hormuz Truce”
Oil prices at the week's close reflect two opposing factors. On one hand, there has been the largest series of attacks on vessels since the war began: following the destruction of five Iranian tankers by U.S. forces, Tehran retaliated by attacking ten ships near the Strait of Hormuz, and the Islamic Revolutionary Guard Corps (IRGC) promised to escalate responses to any further strikes. On the other hand, the Financial Times reported that regional diplomats are attempting to establish a temporary agreement on managing shipping in the strait, which immediately eased some of the geopolitical premium.
The physical landscape remains bleak:
- Transit through Hormuz: On Thursday, only seven vessels passed through the strait, down from eleven the previous day and well below the average of around 15 over the past ten days; prior to the war, about 130 vessels transited daily.
- Saudi Arabia's Production: August output decreased by approximately 1.9 million barrels per day to 6.24 million barrels per day — the lowest level since 1990.
- Second Front in the Red Sea: Houthi forces seized control of Yemen's Mocha port on Thursday, while a series of strikes on facilities in Jazan, Najran, and Abha halted operations at several oil sites and resulted in 73 injuries.
Oil: Price Benchmarks and Forecasts After a Week of Growth
Closing Prices for the Week
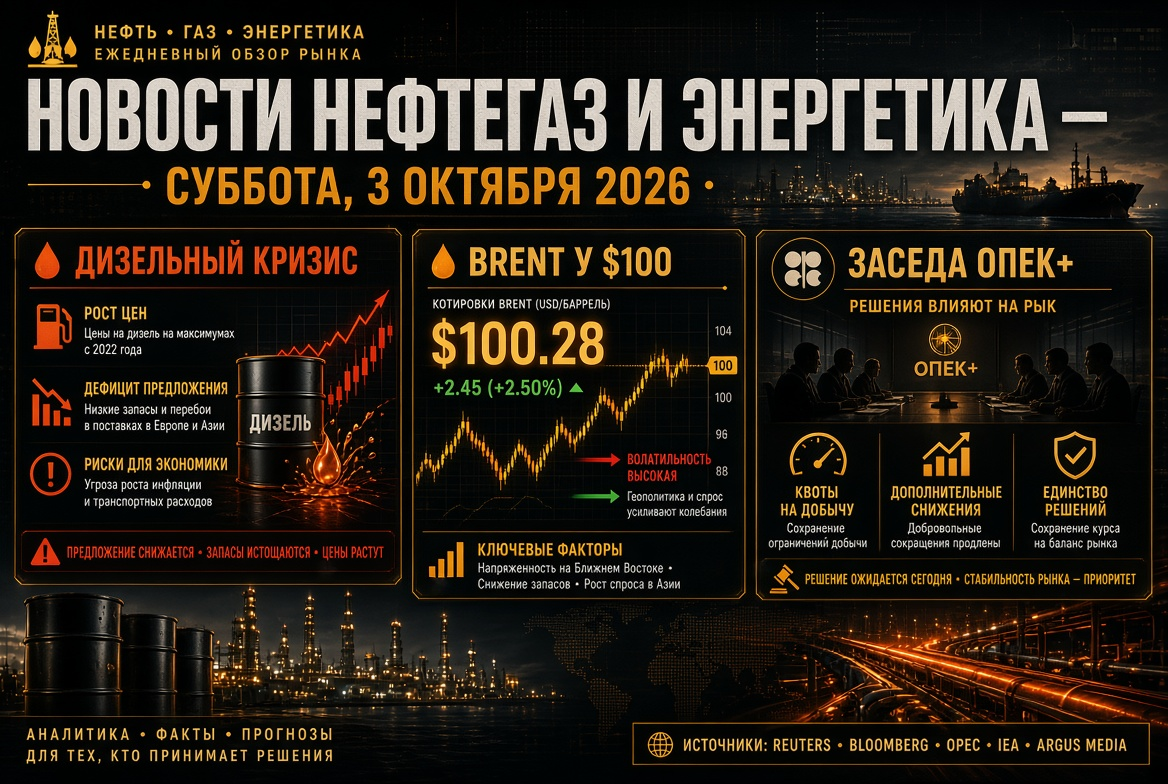
- Brent: Approximately $103–104 per barrel on Friday after intraday highs exceeding $108 on Thursday; a weekly gain of over 7%, with the annual peak of $126.41 (April 30) remaining the upper benchmark.
- WTI: Approximately $99 per barrel after briefly breaking above $100.
- U.S. Inventories: Commercial oil inventories declined by 0.3 million barrels for the week ending September 4; the U.S. Department of Energy subsequently raised its 2027 production forecast to 14.3 million barrels per day.
Revisions of Bank Forecasts
- Commerzbank increased its Brent forecast for the year-end to $85 (up from $75), aviation fuel to $1,230 per ton, and diesel to $1,200 per ton.
- Goldman Sachs expects Brent to reach $85 in December 2026 and $80 in 2027, but acknowledges the possibility of prices exceeding $120 if Gulf production remains 4 million barrels per day below pre-war levels.
- Analysts at UBS and KCM Trade see the risks skewed to the upside amid continued high volatility.
IEA and OPEC: Two Perspectives on Global Oil Market Balance
The IEA’s Friday report was its most stringent since the conflict began. The agency forecasts a decline in global oil demand by 2.5 million barrels per day in 2026 — the largest annual decline since the 2020 pandemic — and a reduction in global supply by 5.7 million barrels per day, or about 6% by 2025. Global inventories fell at a record pace in August — by 3.1 million barrels per day, while the global oil refining system, as described by the agency, "is operating at its limits." A return to surplus has been postponed to 2027.
OPEC on Thursday reduced its growth forecast for 2026 demand for the fifth consecutive month — to 380,000 barrels per day with total consumption at 105.84 million barrels per day — but, unlike the IEA, does not anticipate an absolute decline. For 2027, however, the cartel raised its forecast: an increase of 2.36 million barrels per day to 108.19 million barrels per day, primarily due to China, India, and the rest of Asia. The divergence between the two institutions — over 2.8 million barrels per day for the current year — reflects the level of uncertainty confronting oil companies and traders.
Refined Products and Refineries: Diesel as the Tightest Segment of Global Energy
The refined products market is outperforming crude oil in terms of price increases. The average retail price of diesel in the U.S. has surpassed $6 per gallon for the first time, and crack spreads for middle distillates are holding at multi-year highs. The reasons are a double hit to global refining:
- Restrictions on the export of raw materials from the Persian Gulf and the shutdown of the 400,000 barrels per day refinery in Jazan following attacks from Yemeni territory;
- The Ukrainian campaign of strikes against Russian refineries — with over 70 strikes since the start of 2026, refining in Russia has fallen to a two-decade low.
Russia has extended its ban on diesel exports until September 30 (with a discussion about extending it until the end of the year), while the ban on gasoline exports remains in place until January 31, 2027, and for jet fuel until the end of November. For the first time in decades, Moscow is importing fuel and has arranged for oil processing at a private refinery in Kazakhstan. China, for its part, will increase retail price caps for gasoline and diesel by 260 and 250 yuan per ton, respectively, starting September 12 — a signal that the price shock has reached regulated markets in Asia.
Gas and LNG: Europe Enters Winter with TTF Above €80 and Storage at 67%
The European benchmark TTF adjusted to €80.75 per MWh on Friday (a decrease of 1.6%), remaining near its highs since December 2022. The price has risen by 32% over the month and by 147% over the year. The blockade of the Strait of Hormuz disrupted around 20% of global LNG flows, primarily from Qatar, and European storage facilities are filled to only about 67% compared to the seasonal norm of over 80%. QatarEnergy maintains its target of restoring 50% of capacity within a month after navigation normalizes, but without safe passage for tankers, this remains a declaration. Against this backdrop, two ECB representatives on Friday suggested further rate hikes if energy inflation continues to spill over into other prices in the eurozone — a factor that limits speculative demand for commodities.
Coal: Twelve-Week High Amid Gas Switch
Newcastle thermal coal traded around $148 per ton on September 10 — a twelve-week high, with a rise of 14.5% over the month and nearly 47% over the year. The LNG deficit is driving coal generation in Northeast Asia and parts of Europe, while global electricity consumption, fueled by data centers and air conditioning, slows the displacement of coal. A curious paradox: China has officially reported that solar energy has surpassed coal for installed capacity for the first time, yet, in actual generation, coal remains the largest source of electricity in the world.
Electricity and Renewables: Structural Trend Against Short-Term Chaos
The energy transition remains the only predictable trend in the sector. China leads in investments, patents, and exports of clean technologies, India is building renewable capacity faster than it can utilize it, and in Europe, an excess of solar and wind generation amid a lack of storage increasingly leads to negative electricity prices during daytime hours. Each euro increase in TTF boosts the economics of battery storage, grid investments, and long-term contracts for “green” energy. Corporations are reshaping their portfolios: Shell has sold a gas power plant in the U.S. for $715 million, while Enbridge is acquiring the Tallgrass pipeline business for $2.55 billion, betting on oil transportation infrastructure.
Logistics and Freight: Tankers as the New Bottleneck
Even with physical volumes, oil exports from the Gulf are constrained by a shortage of vessels. The VLCC freight rate on the Middle East to China route reached a record nearly $800,000 per day, while transport from the U.S. Gulf to Asia costs $29.5 million per trip, excluding military risks. Redirecting Saudi shipments via the Red Sea and the Mediterranean extends voyages by 30 days and ties up the fleet, exacerbating the tonnage shortage for all exporters.
What Market Participants Should Watch for Over the Weekend
- Any confirmations or refutations of a temporary shipping agreement in the Strait of Hormuz and Tehran's reaction.
- Statements from the Yemen coalition following the seizure of Mocha and the status of the Yanbu terminal — the last major bypass channel for Saudi oil.
- The dynamics of injection into European storage facilities and the JKM-TTF spread as an indicator of spot LNG competition.
- Signals from the Federal Reserve and the ECB: a tightening rhetoric could cool the commodity rally regardless of geopolitics.
- Decisions from Russian regulators regarding export restrictions and fuel imports before the heating season starts.
Conclusions and Risks for Investors and Energy Sector Companies
- Oil. The $100 mark has established itself as support; a diplomatic breakthrough concerning Hormuz could quickly drive Brent to $85–90, while new attacks on vessels could pave the way to $115–120.
- Refined Products and Refineries. Middle distillates remain the tightest segment; margins for refiners outside the conflict zone are at historical highs, and retail prices are a source of political pressure from the U.S. to China.
- Gas. Europe enters the heating season with historically low inventory levels; TTF above €90–100 during a cold winter is the baseline, not a stress scenario.
- Coal. Increased demand in Asia and Europe will persist at least until Qatar's LNG recovery.
- Renewables and Electricity. The capital flow into solar and wind generation, storage, and grids is accelerating, but short-term stability of energy systems still depends on gas and coal.
The week's outcome for global oil, gas, and energy: the market has, for the first time in months, received a hint of a diplomatic exit from the Hormuz deadlock, but physical indicators — from record diesel prices to the lowest Saudi production since 1990 — indicate that the deficit will dictate prices for oil, gas, and electricity for weeks to come. For energy market participants, scenario planning, logistics diversification, and hedging discipline are critically essential.